
The week that was (April 9-13)
CBN lowers OMO clearing rates: In response the continued downtrend in the inflation rate, the CBN lowered discount rates at the Open Market Operations (OMO) bill auction to 12.2% (previously 12.6%) and 13.99% (previously 14.4%). At the auction, the CBN sterilized NGN500billion, relative to OMO maturities of NGN476billion, which drove a mild uptick (average 10bps) in benchmark Nigerian Treasury Bill (NTB) yields. Nonetheless, system liquidity continued to remain sizable which held OBB/Overnight rates down at 2.33/2.9%. For the record, the 91-day (discount: 12.76%, effective 13.18%), 182-day (discount: 13.36%, effective 14.31%), and 1yr (discount: 13.21%, effective 15.16%). However, farther out, bond markets went bullish in response to the subdued inflation numbers with 40bps decline in yields over the week.
Disinflation continued in March: The National Bureau of Statistics published inflation numbers on Thursday which showed further slowdown in March to 13.34% y/y primarily driven by base effects. Monthly inflation printed at 0.84% (Feb: 0.8%) extending the sub 1% pattern over Q1 2018 which is a departure from the 1.3% average in 2016-17. This is consistent with a normalization in inflation expectations as the exchange rate has remained fairly stable. Furthermore, an improving fuel supply picture with the national fuel price average sliding to NGN163/litre is providing support for a downleg in inflation. For April, my forecast is for a 12.4% y/y CPI print.
Figure 1: NGN Yield Curve
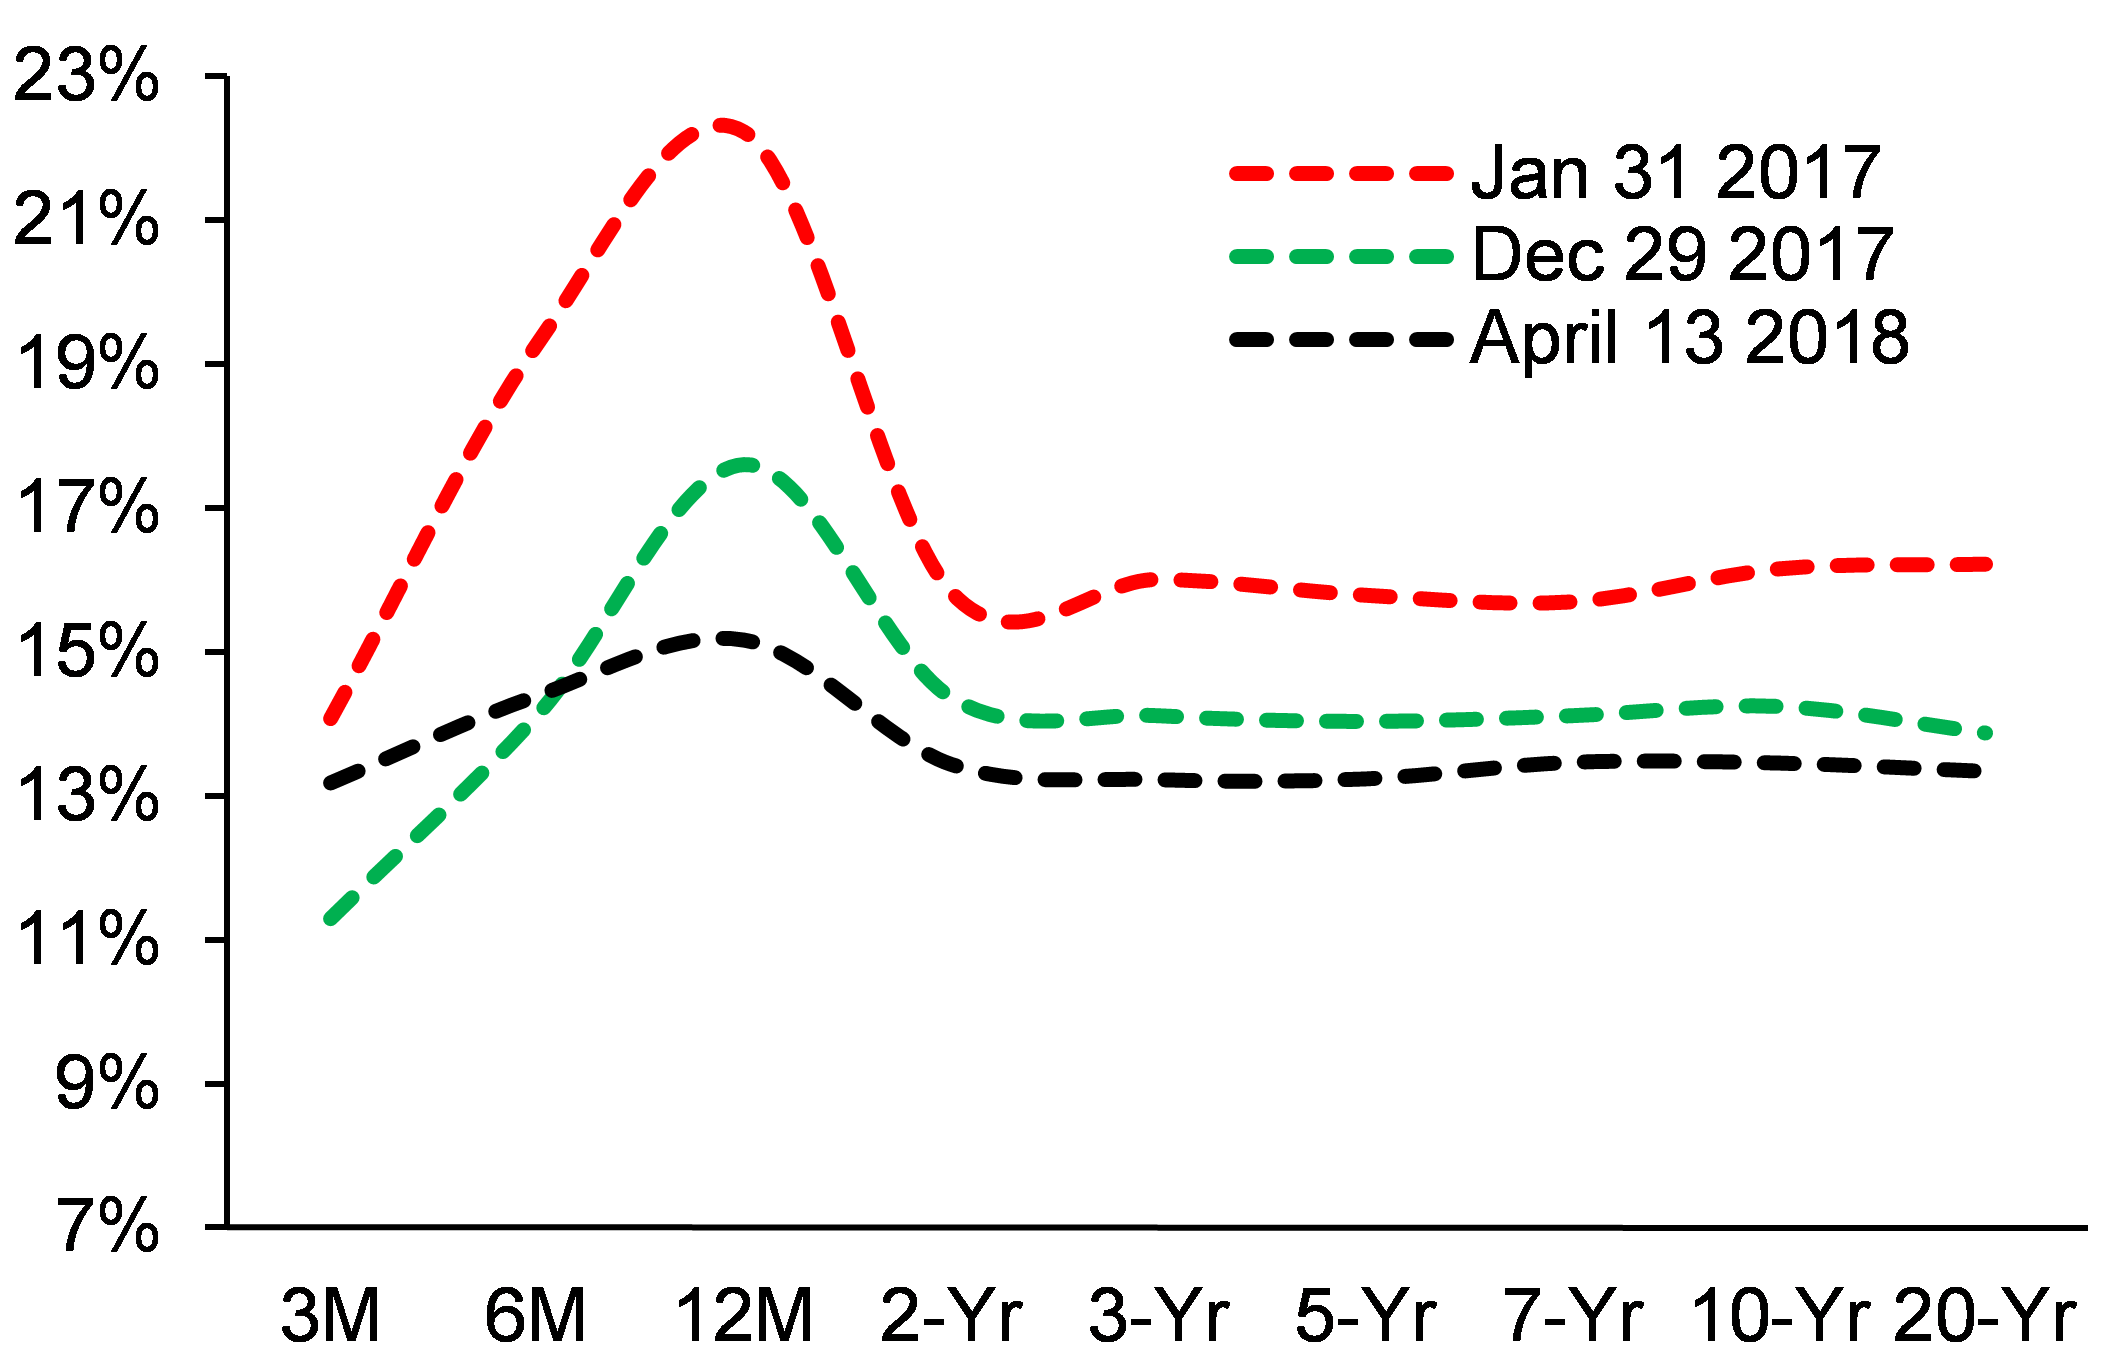
Source: FMDQ
The Week ahead (April 16-20)
In the ahead, consistent with its reduced borrowing plan, the CBN, on behalf of the FG, will sell NGN58billion at the NTB auction on Wednesday relative to around NGN116.9billion worth of NTB maturities on Thursday. Alongside OMO maturities of NGN276billion on Thursday, liquidity levels look set to pose fresh downside pressures to NTB yields. In addition, debt markets will look forward to the release of the DMO borrowing calendar for Q2 2018 over the week. Given NGN300billion in bond maturities over the quarter, markets are likely to turn bullish if issuance is in line with the NGN254billion in Q1 2018 which is likely in view of stronger oil price (USD71/bbl as at last week against USD48/bbl in the proposed 2018 budget). In all the backdrop suggests a bullish week for debt markets.
Discover more from Eco215
Subscribe to get the latest posts sent to your email.