
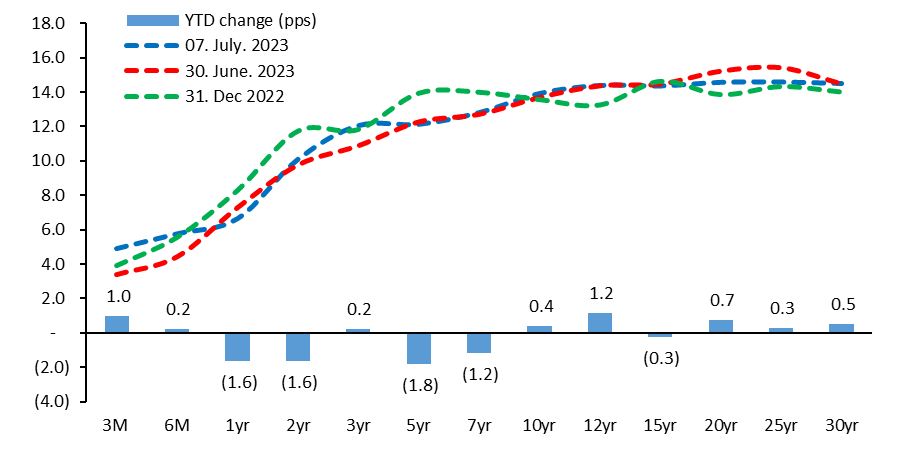
Robust liquidity conditions continue to drive yields lower: Domestic money markets remained sufficiently liquid, the aftermath of CBN’s decision to return to an equitable CRR regime, with daily opening positions at NGN700-800billion. The liquidity overhang kept interbank rates depressed at 1-2% with a knock-on effect on yields which slid 15bps over the week. Though markets were spooked by a glitch which suggested thinner system liquidity, with a brief sell-off, this turned out to be a FUD (to borrow slang from crypto) and buying activity swiftly resumed. In the absence of any liquidity outflow events, all eyes are now on the July 2023 bond auction and the MPC meetings. The DMO is likely to take advantage of the large coupon inflows alongside the existing liquidity to reprice the bond sale at lower yields to reflect market realities. The CBN should clarify its real posture on the currently loose liquidity conditions at the two-day MPC meeting for July.
Figure 1: Naira Yield Curve
Source: FMDQ
Naira comes under renewed weakness, CBN continues to tweak market architecture: The NGN weakened at the IE window (down 1.0% to NGN776/$) and parallel market (down to ~NGN790/$). The FMDQ (which runs the FX market exchange and which is a CBN associate company) announced some changes to the method of computing the NAFEX and IE exchange rates to reflect actual transaction data vs the prior approach of using indicative quotes supplied by banks. Furthermore, the CBN appears to have given the greenlight to the large IOCs to sell dollars to banks, a departure from the prior arrangement where these sales were to the CBN. This should improve USD supply within the IE window which remains soft. External reserves slid to USD34billion despite stronger prices and improved production levels since 2023. This continues to reflect the impact of the now discontinued crude-refined product swaps which weighed on FX reserve inflows.
In the week ahead, there will be an NTB auction on Wednesday, where the CBN, on behalf of the DMO, will look to rollover NGN142billion worth of maturing NTBs. Given the very liquid conditions, expect yields to test fresh lows. This week sees the maturity of the Nigeria’s 6.375% July 2023 Eurobond issued in 2018 with a face value of USD500million. A successful redemption on Tuesday 12th July will continue Nigeria’s track record of meeting principal repayments (after 2018, 2021 and 2022) at a time when there is significant doubt over the USD repayment of some better rated SSA sovereigns.
It’s Adam Smith’s 300th birthday so I will closing out July with some quotes by the great economist.
The great source of both the misery and disorders of human life, seems to arise from over-rating the difference between one permanent situation and another. Avarice over-rates the difference between poverty and riches: ambition, that between a private and a public station: vain-glory, that between obscurity and extensive reputation. The person under the influence of any of those extravagant passions, is not only miserable in his actual situation, but is often disposed to disturb the peace of society, in order to arrive at that which he so foolishly admires. The slightest observation, however, might satisfy him, that, in all the ordinary situations of human life, a well-disposed mind may be equally calm, equally cheerful, and equally contented. Some of those situations may, no doubt, deserve to be preferred to others: but none of them can deserve to be pursued with that passionate ardour which drives us to violate the rules either of prudence or of justice; or to corrupt the future tranquillity of our minds, either by shame from the remembrance of our own folly, or by remorse from the horror of our own injustice.” ― Adam Smith, The Theory of Moral Sentiments
if you would like to receive this every week as well as other posts or you know someone who will find the information on this site useful, you can add your email using the subscribe button below.
Discover more from Eco215
Subscribe to get the latest posts sent to your email.